Choose Your Plan Like You Know Your Body: An Open Enrollment Strategy Built on Real Health Needs
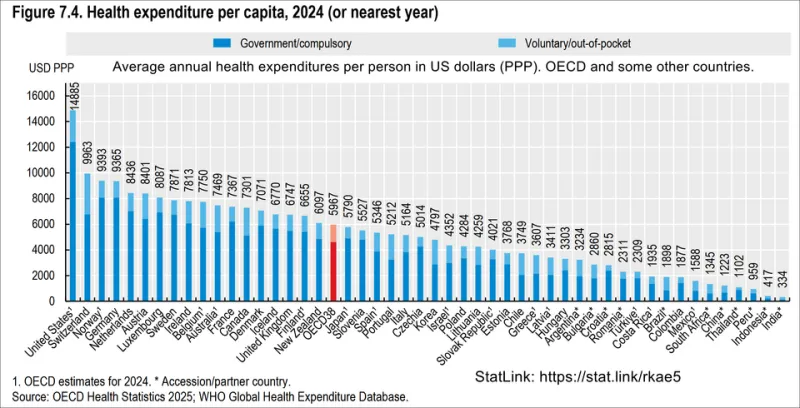
Photo: OECD. Also, text was added via an image editor such as freeware IrfanView., Public domain, via Wikimedia Commons
Every autumn, millions of Americans face the same deadline and make the same mistake: they choose a health plan by finding the lowest monthly premium and clicking confirm. It feels prudent. It is, in fact, a bet—usually a losing one—that nothing will go wrong with your body for the next twelve months.
The alternative takes perhaps two hours and a recent prescription bottle. Here is how to run it.
Start With an Inventory, Not a Spreadsheet of Premiums
Before you look at a single plan, write down what your health actually required this year and what it is likely to require next year:
- Medications, including dosages and whether they are brand-name or generic
- Regular providers: primary care, any specialists, therapists, dentists if dental coverage matters
- Expected care: a planned procedure, a pregnancy, a knee that has been talking to you
- Recurring costs: therapy sessions, allergy shots, medical equipment
This list is your shopping specification. A plan is not good or bad in the abstract; it is good or bad for this list.
Check the Formulary Before You Check the Price
Every plan maintains a formulary—a list of covered drugs, usually arranged in tiers. The same medication can cost $10 on one plan and $180 on another, or be excluded entirely. Insurers also change formularies between plan years, so last year's coverage proves nothing.
Look up each of your medications on the plan's formulary and note:
- Whether it is covered at all
- Which tier it sits in (generic, preferred brand, specialty)
- Whether prior authorization or step therapy is required
- What you pay during the deductible phase, not just after it
If you take a specialty drug—a biologic, an injectable, anything requiring refrigeration or pharmacy coordination—this step is not optional. It is the entire decision.
Verify the Network Twice
Provider directories are notoriously stale. Verify that your doctors participate in each plan you are considering, then confirm again directly with the provider's office. Ask specifically about the plan name and network—large insurers run multiple networks, and a doctor in network for one may be out of network for another.
If you are managing a chronic condition, also check the key facilities: the hospital where your specialist operates, the imaging center, the lab. Out-of-network facility charges are among the most common sources of surprise billing.
Do the Real Math on Deductibles and Maximums
The premium is the only number on the plan page you can be certain of paying. Everything else depends on how much care you use. So estimate honestly:
- If you are healthy and rarely see a doctor, a lower-premium, higher-deductible plan paired with a health savings account (HSA) may genuinely serve you—provided you can fund the HSA.
- If you have predictable costs—a monthly medication, quarterly visits—run the total: premium times twelve, plus your estimated share of care under that plan's deductible and copays. Compare that figure across plans. The cheapest premium is frequently not the cheapest year.
- If you expect major care, the out-of-pocket maximum is the number that matters most. It caps your worst-case exposure, and plans differ by thousands of dollars on it.
Match the Plan Type to Your Temperament
HMOs reward staying inside the network and require referrals for specialists. PPOs cost more but offer flexibility and direct specialist access. High-deductible plans pair with HSAs and suit people who can absorb risk. There is no universally correct structure—only the structure that fits how you actually behave when you are sick at 9 p.m. on a Tuesday.
Two Details People Skip
First, check whether your plan covers telehealth and at what cost; for many households it has quietly become a primary care channel. Second, if you have an HSA or FSA, note the contribution limits and any use-it-or-lose-it rules for the coming year.
The Deadline Is a Clinical Event
It may feel strange to call an insurance decision a health decision. But the plan you choose determines whether you can afford the medication you take daily, whether you keep the doctor who knows your history, and whether a recommended screening becomes a receipt or a bill. Open enrollment is the one week a year when you get to design your own access to care. Spend the two hours. Your future self—possibly a sick one—will be glad you did.